
What Should I Do if My Insurance Keeps Denying My Claims
Repeated denials usually mean you need to challenge the decision in writing and document everything before you accept the outcome.
Denials follow rules you can push back against
An insurer denies a claim when it decides the policy doesn't cover what happened, or when it thinks the paperwork doesn't support your version of events. Sometimes that's accurate. Often it's a starting position, not a final one, especially if the first denial came quickly or without much explanation.
Claims adjusters work from the file in front of them. If that file is thin, missing photos, missing a police report, missing a clear timeline, the denial reflects the gap, not necessarily the truth of what happened. Filling that gap and resubmitting is often enough to change the result.
When a second request still gets denied, the reason usually sits in one of two places. Either the policy genuinely excludes what happened, which you can confirm by reading the actual policy language rather than the denial letter's summary of it, or the insurer is applying the exclusion too broadly. Your state's insurance department can tell you which exclusions are standard and which ones get challenged successfully.
A pattern of denials across different claims is different from one denial on one claim. If every claim gets questioned, that's a signal about this specific insurer's practices, not about your driving or your luck. That's the point where shopping around stops being about price and starts being about whether this company pays out at all.
Is it worth hiring a lawyer or public adjuster to fight a denial?
It's worth it once the claim amount is large enough that professional help would cost less than what you'd recover, which is usually true for serious accidents, total losses, or injury claims, and less true for small repair bills.
For smaller claims, your state insurance department's complaint process is free and often faster, since insurers tend to respond quickly once a regulator is copied on the correspondence. Save legal help for claims where the insurer is disputing fault, disputing injury, or denying a large total loss, since those cases involve more judgment calls and more money on the table. Ask any lawyer about the fee structure before you sign anything, since many work on contingency for these cases.
Whether you formally dispute the denial in writing
If you do
You create a paper trail that forces the insurer to respond to specifics instead of a form letter. You can cite your policy language, attach evidence, and request a clear reason for denial. This often gets a claim reopened or escalated to a supervisor who looks at it fresh.
If you don't
The denial stands as the final word with nothing on record showing you pushed back. If you later need to escalate to a state regulator or small claims court, you'll have no documented attempt to resolve it directly first, which weakens your position.
Once you know how to handle a denial, compare quotes to see if another insurer would have paid the claim.
A denied claim after a parking lot collision
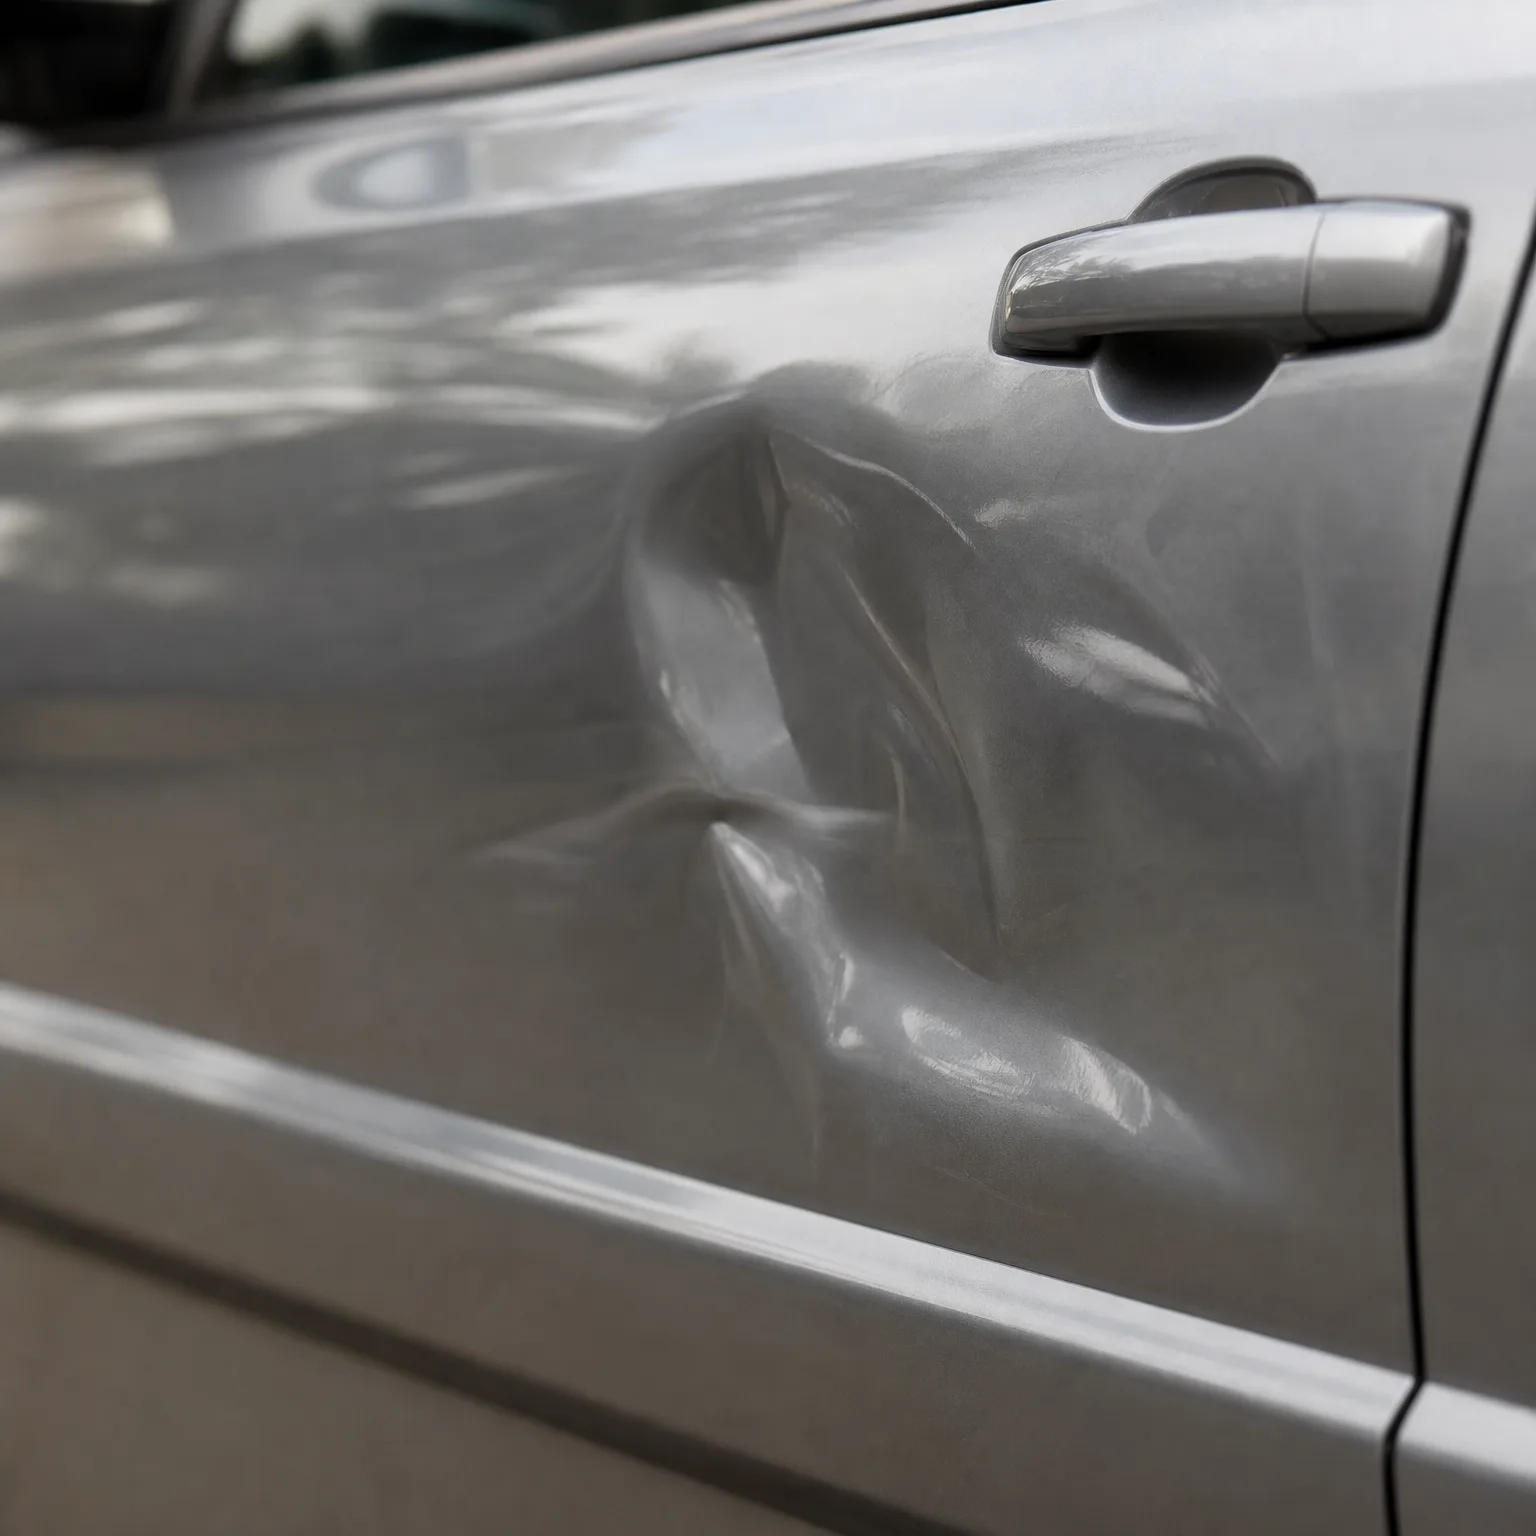
You backed into another car in a parking lot and filed a claim. The insurer denied it, saying the damage didn't match your description of the incident. You went back to the scene, took photos of the skid marks and the angle of the dent, and got a written statement from a witness who'd seen it happen.
You resubmitted with the new evidence and a short letter explaining exactly where the adjuster's report differed from what actually happened. Two weeks later the claim was approved and paid at the original estimate. The difference wasn't a new argument, it was simply giving the adjuster something concrete to approve instead of a dispute to sit on.
A denial is a position the insurer took with the information it had, not a verdict you have to accept.
How long do I have to appeal a denied car insurance claim?
It depends on your state and your policy, often somewhere between several months and a year, so check the denial letter itself, which should state a deadline. If it doesn't, call and ask directly, then confirm it against your state insurance department's rules, since some states set a minimum appeal window regardless of what the insurer's letter says. Missing this deadline can end your options, so treat it as the first thing to check, not an afterthought.
Can I file a complaint against my insurer with the state?
Yes, every state has an insurance department that handles complaints about denied claims and unfair practices. Filing is usually free and done online or by phone, and you'll need your policy number, the denial letter, and a short summary of what happened. Regulators can't force a payout, but they can require the insurer to respond formally and explain its reasoning, which often moves a stalled claim.
Should I switch insurers after a claim gets denied?
If this is the first denial you've experienced with this insurer, it's worth resolving the claim first before deciding. If you notice a pattern across multiple claims, or the denial process felt evasive rather than evidence based, that's a strong reason to get quotes elsewhere. Check reviews specifically about claims handling, not just price, since that's the part that matters when something goes wrong.


