
What Is the Downside of Having a High Deductible
A high deductible lowers your premium but raises what you owe the moment you actually file a claim.
You're trading a smaller bill now for a bigger one later
A deductible is the amount you agree to cover yourself before the insurer pays anything on a claim. When you raise it, you're telling the insurer you'll absorb more of the small and medium damage yourself, and they charge you less for that promise because they expect to pay out less often. The downside shows up the moment something actually happens to your car, because that number you picked on a form becomes real money due right away, often before a repair shop will even start work.
The risk isn't evenly spread. A high deductible costs you the most on small to moderate damage, the kind that's just above or even below what you chose, because you end up paying close to the full repair cost yourself and the insurance barely helps. On a major claim, like a serious accident or a total loss, the deductible is a smaller share of the total, so the downside matters less there.
There's also a behavioral cost people don't plan for. With a high deductible, minor dents, cracked glass, or a small parking lot scrape often aren't worth filing a claim over at all, since the payout after your deductible might be tiny or nothing. That means you're effectively self-insuring for a whole category of damage, not just choosing a number.
How this plays out depends on your insurer's claim thresholds and your state's rules around things like glass repair or minimum coverage, so check your policy documents for how the deductible applies to each type of claim, since comprehensive and collision deductibles aren't always the same amount.

Where a high deductible actually hurts you
- Out-of-pocket cash You need that deductible amount available right after an accident, often before repairs start. If you don't have it sitting in savings, a high deductible can leave you stuck.
- Small claims aren't worth it Minor damage often costs less to fix than your deductible, so you pay the whole thing yourself. The insurance effectively does nothing for everyday fender benders.
- Repairs get delayed or skipped Facing a large out-of-pocket cost, some people put off fixing dents or glass damage. Deferred repairs can turn into bigger problems or lower resale value.
- Two deductibles can stack Comprehensive and collision deductibles are often separate amounts. A claim involving both situations, like hitting an object after a tire blowout, can mean paying twice.
- Harder to budget for A high deductible only helps if you can genuinely afford it when something happens. Picking one that's too high for your actual savings undoes the premium savings.
Choosing a high deductible to save on premium
If you do
Your premium drops each time it's billed, freeing up cash now. But after any accident, you'll owe that higher amount before insurance covers the rest. Small dents and minor damage often aren't worth claiming at all, so you're quietly taking on more risk than the lower bill suggests.
If you don't
You keep a lower deductible and pay more in premium every billing cycle, even when you have no claims at all. In exchange, if something happens, your out-of-pocket cost stays small and predictable, and filing a claim for minor damage still makes financial sense.
Compare quotes at a few deductible levels so you can see exactly what each one trades off before you decide.
What deductible should I actually pick?
Pick the highest deductible you could pay in cash today without it disrupting your life, and no higher. That's the real test, not what lowers your premium the most. If an unexpected bill at that amount would mean missing rent or going into debt, the deductible is too high for you right now, regardless of the savings on paper.
Think about it alongside your emergency savings rather than in isolation. If you already keep a cushion for unplanned expenses, a higher deductible is reasonable because you're genuinely prepared to use that cushion. If your savings are thin after a recent move or a down payment, a lower deductible keeps a bad week from becoming a bad year, even though you'll pay a bit more for that protection every term.
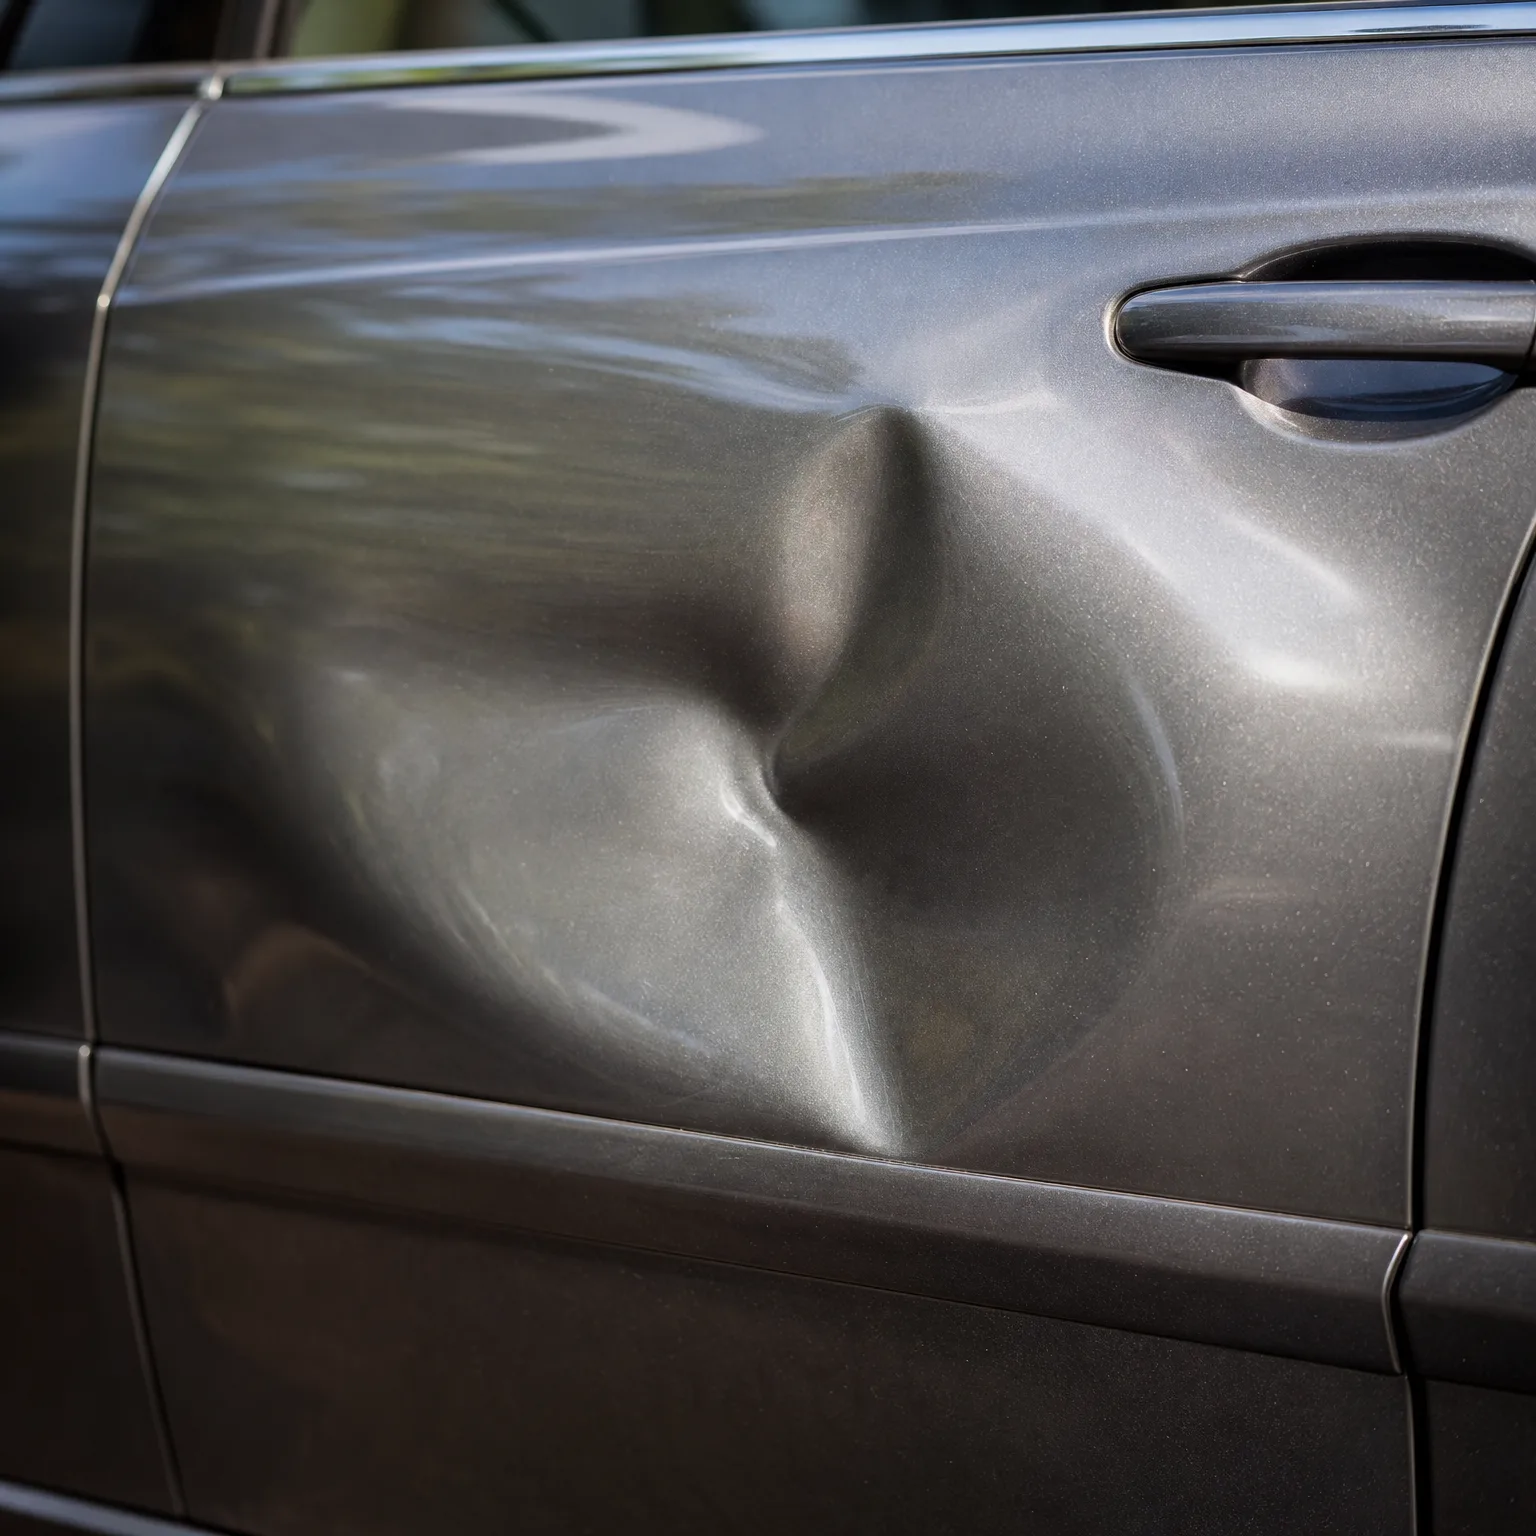
A driveway scrape after moving to a new place
Say you raised your deductible right after buying your home, because the lower premium looked appealing with a mortgage payment now in the mix. A few months in, a neighbor backs into your car in the shared driveway and the damage comes in modestly above your old deductible but now sits right at your new, higher one. You check your policy and realize filing a claim would mean paying almost the entire repair cost yourself.
You decide to get a couple of repair quotes before doing anything else, since the damage is cosmetic and not affecting how the car drives. One quote comes in close to your deductible amount, so filing a claim wouldn't actually save you much once you account for it. You pay out of pocket, skip the claim, and keep your claims history clean, which also protects your premium down the road. It works out fine this time because you had the cash ready, which is the part that made raising the deductible a reasonable call in the first place.
How much should I keep in savings if I raise my deductible?
Keep at least your full deductible amount set aside and easy to access, separate from other savings goals. That way a claim doesn't force a hard choice between repairing your car and covering rent or groceries. If you're also holding a cushion for job loss or medical costs, add the deductible on top rather than counting it as part of that same fund.
Does a high deductible affect how fast a claim gets paid?
No, the deductible doesn't change claim processing time, only how much the insurer pays you at the end. Processing speed depends on your insurer, the complexity of the damage, and whether liability is disputed. Check your insurer's typical claim timeline separately, since that's usually listed in your policy materials or available by asking directly.
Can I change my deductible back if money gets tight later?
Yes, in most cases you can lower your deductible at your next renewal or sometimes mid-term, though your premium will rise to match. Check with your insurer about timing and whether a mid-term change is allowed, since some require waiting until renewal. If your financial situation has shifted since you first chose it, it's worth revisiting.


